Wednesday, June 27, 2012
Employers can structure PRS to retain talent, save tax
KUALA LUMPUR (June 6): Employers can take full advantage of the tax benefits for their contribution to employee remuneration, while retaining their talent pool, by participating in private retirement schemes (PRS) that are set to come into the local market as early as October.
Jason Chong, CEO of Manulife Asset Management (M) Sdn Bhd, said PRS can be structured to become a talent retention tool for the employer. "Vesting is one way. I give you an additional 3%, but if you leave within two years, you don't get anything. It can be a progressive scale. We hear about brain drain all the time… people going to work in Singapore and Hong Kong. This is one way of retaining talent in Malaysia," Chong said on Tuesday.
Moreover, the Malaysian tax structure allows employers to claim tax deductions of up to 19% of their employee remuneration under employment benefits, which is above the current statutory contribution rate of 12% or 13% to the Employees Provident Fund (EPF).
"Currently, employers give 12% [or 13% for employees whose monthly salary is below RM5,000], so potentially there is another 7% that they can contribute and still get tax deductions," Chong said, pointing out that statistics show most retirees using up an average of RM150,000 from their EPF savings within the first three to five years of retirement.
While tax benefits could help spur the initial take-up of PRS, Chong reckons individuals themselves need to understand what PRS is and whether the options available could help shore up savings for their old age. "There will need to be a lot of education on benefits, but that's part of the business plan."
Individuals can claim RM3,000 tax relief a year on voluntary contributions to PRS.
Manulife Unit Trust Bhd was among the eight Securities Commission Malaysia-approved PRS providers announced on April 5. The others were AmInvestment Management Sdn Bhd, American International Assurance Bhd (AIA), CIMB-Principal Asset Management Bhd, Hwang Investment Management Bhd, ING Funds Bhd, Public Mutual Bhd and RHB Investment Management Sdn Bhd.
Basic PRS products should come into the market from October this year, as the providers were given six months to come up with a plan for approval, Chong said. Market conditions should not affect the roll-out as the product is for the long term, he added.
The common questions that come up are: Can the PRS beat the EPF in terms of returns? And what happens if the fund ends up giving lower returns than the EPF?
"It depends on your risk appetite, growth, moderate or conservative. If you're aggressive and go for the more aggressive growth products, then you should. But if you're conservative, you go for the more conservative funds," Chong said.
"Part of the education process is to not look so much at the short-term performance, but at the long-term performance… sometimes [due to market conditions], you can't look over the one-year basis. You've got to look over the medium term," said Chong, who is not expecting a strong take-up until there is more awareness about PRS.
Studies have shown that putting money with Manulife funds delivers 200 basis points more returns a year on average over a 10-year period, net of management fees, than if one were to invest their money themselves, said Robert Boyda, head of Global Asset Allocation and senior portfolio manager for Manulife Asset Management in the US, where Manulife is the No 1 private pension scheme provider. It is also No 1 in Canada and No 2 in Hong Kong and Indonesia.
The difference of having funds professionally managed, Chong added, minimises the paralysis of herd mentality that individual investors are often caught in.
"When you invest yourself, you are hit by sentiment, you become emotional. When the market crashes, you panic and you sell. When the market rebounds, you miss the rebound because you're scared to jump back in wondering if [the uptick] is sustainable. A pension fund will take a long-term view and sit through [the shorter-term volatilities]," he said.
Sharing her experience in the Hong Kong market, Luiza Rosa Hung, CEO Manulife Provident Funds Trust Co Ltd, said the facilitation of an automatic enrolment on the private retirement scheme plans, while allowing the choice to opt out, could increase the chances of an individual saving more for their retirement. To ensure sustainability, the process for wage earners to make additional voluntary contributions should be simple, she added.
Source: This story appeared in The Edge Financial Daily on June 6, 2012
Tuesday, June 26, 2012
避免爭議‧單身人士應立遺囑
一個單身的成年人,如果去世前沒有立遺囑,同時父母已不在世、在沒有配偶、子女的情況下,根據遺產法令的分配,遺產歸兄弟姐妹平分。
一名自稱是單身的讀者說,她名下有一些資產,例如房屋、單位信託、銀行存款,汽車等等,她想知道,如果是亁兒子,可以直接割名給他嗎?
__________________________________________________________________________________
答:單身的女姓朋友應該立遺囑,立了遺囑,可以將財產分配好,列明其中一部份財產將分給亁兒子,假如沒有立遺囑,萬一不在世,遺產將根據遺產法令分配。
林若輝律師說,一個單身的成年人,如果去世前沒有立遺囑,同時父母已不在世、在沒有配偶、子女的情況下,根據遺產法令的分配,遺產歸兄弟姐妹平分。
財務顧問認為,單身的成年人,不論財富多少,都應該立遺囑,立遺囑的時候,可以依據個人的意願進行遺產分配,譬如可以分配給母校、宗教組織、社會團體,侄兒、侄女、外甥等,表明分配同樣或不同數目的款項。
我們有遇到這樣的情況,就是單身的成年人去世,生前沒有立遺囑,財產說多不多、說少不少,其兄弟姐妹也過得去,他們因沒有時間處理,沒有打理其遺產。
另外一種情況是,儘管是以遺產法令進行分配,兄弟姐妹平分,可是,兄弟姐妹之間各說各話、互不相讓,認為自己應該分多一些,因為無法達致協議,鬧到不歡而散,結果也是沒有人負責處理,遺產最後只好歸政府。
一個人在世時,若立了遺囑,可以根據自己的判斷、意願來分配自己的財產,其他人不能有任何異議。
Source: (星洲日報/投資致富‧產業問診室)
Tuesday, May 8, 2012
保险金字塔
保险三重功用:保障,保证,保全
第一重:保障的是现有的生活
保全的是责任,这是风险管理
第二重:保证未来的幸福
保证的是未来,这是风险投资规划
第三重:保全已经创造的财富
保全的是成就,这是资产配置
当物质生活水平不断走高,人们的幸福感却没增加,反而越来越低。我们必须面对失业问题,养老问题,医疗问题,子女上学问题,还要面临交通意外,生活食品安全的隐患,环境污染和新食物链中致癌物质的侵害,以及社会持续通货膨胀所需的理财规划等等。
面对生老病死,无人可以回避,人们之所以表现出前所未有的忧虑,就在于对未来人生不测的担忧和恐慌。这些担忧无法为其他商品代替,可以人寿保险的十大黄金价值所解决:
1。爱有所继;2。亲有所奉;3。病有所医;4。壮有所倚;5。残有所仗;
6。钱有所积;7。幼有所护;8。老有所养;9。产有所保;10。财有所承
我把以上的资料整理然后再把它编成了解图,以方便大家容易的参考:
click to enlarge the pic
希望这个解图可以让大家更容易的明白人寿保险的功能和价值
Sincerely,
Tan Min Chin, CH3
Wednesday, May 2, 2012
Cost of Delay - Senario 3
Assumption:
1. Both Prospect A and B
are age 30, they want to save for their retirement by the age of 55.
2. Prospect A saves 25
years with payment amount of RM6,000 with 8% interest.
3. Prospect B delays his
saving 5 years later. He pays continuously until the age of 55 with the same
payment amount and interest as Prospect A.
Conclusion:
1. Prospect A gets RM473,726.48 by the age of 55 with an amount of RM150,000 invested.
2. Prospect B is
Postponing 5 years and he would get RM296.537.53 by the age of 55 with an amount of
RM120,000 invested.
3. Although Propect B pay
RM30,000 lesser than Prospect A, but Prospect A earn RM177, 188.95 more than Prospect B.
Click to enlarge the picture
The sooner you start, the MORE you get ;)
Sincerely,
Sunday, April 29, 2012
Six budget superfoods
They are said to help us maintain
weight, fight diseases, live longer and even look more beautiful, but as
nutritionists point out, ‘superfoods’
are no more than a marketing term, and while not all foods are created
equal, you can find options that give you the same benefits and at a
much lower cost.
Early this year, for instance, the BBC reported that a Dutch scientist had advocated bugs as a green superfood, arguing that insect dishes, boasting a lower carbon footprint in addition to being very nutritious, could be the answer to the global food crisis.
While that may be the case, nutritionists point out that “superfood” is a term created by marketers and does not exist technically. Nutritionist Tan Sue Yee says, “All types of foods contain their own nutrition profiles, and a varied diet is recommended to obtain a myriad of nutrients for health and well-being. The so-called ‘superfoods’ that we often read or hear about are mostly foods that are grown abroad. Thus, they are often less available and costly in Malaysia.”
Wong Yu Jin, a nutritionist and wellness coach, points out that the humble sweet potato has more antioxidants than blueberries, which are often listed as a superfood.
He adds that the term ‘superfood’ also gives the impression that once you have eaten such food; you don’t have to worry about other areas of your diet.
“The hype surrounding superfoods has become so hot that companies are now selling superfood pills, extracts and elixirs, claiming to offer various health benefits such as anti-ageing, cancer fighting and detoxification.”
If you’re keen on a super diet without breaking the bank, here are some alternatives.
1) Blueberries
Blueberries are a top choice of those promoting superfoods, and there is no doubt that they are high in potassium and vitamin C.
A 100g serving packs 77mg of potassium, 9.7mg of vitamin C and 6mg of
calcium, among others. But at RM16 for a 125g punnet, they are beyond
the budget of many.
The alternativeThe humble pineapple, which is widely available at supermarkets and local wet markets, is only RM3.50 a kg, and it packs a punch nutrition-wise. A 100g serving offers 97mg of potassium, 15.2mg of vitamin C and 24mg of calcium.
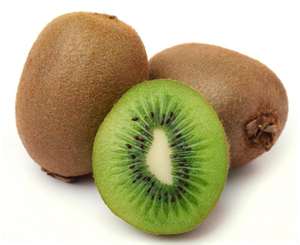
2) Kiwi fruitTouted as a nutrient-rich food, the New Zealand export has more potassium than bananas or citrus fruits and is an excellent source of vitamin C. A 100g serving boasts 180mg of potassium and 86.7mg of vitamin C, but it also packs a wallop on the wallet at RM7.90 for a packet of four (weighing about 600g).
The alternativeWhile the guava (at RM4.90 a kg) may not boast a high concentration of potassium (29mg per 100g), it is still packed with nutrients. A 100g serving boasts 152mg of vitamin C, 10mg of vitamin A and 33mg of calcium.
3) PomegranatePomegranates are being hailed as a superfood that can protect the heart. A 2004 BBC report states that scientists in Israel have shown that drinking a glass of pomegranate juice daily could reduce the risk of cardiovascular disease. A 100g serving of the fruit has 236mg of potassium, 10.2mg of vitamin C, 10mg of calcium and 4g of fibre. At around RM3.30 a fruit, it may put a large dent in one’s wallet.
The alternativeThe dragon fruit (RM2.50 each) may lose out to the pomegranate in terms of calcium (8.8gm) and fibre content (0.9g of fibre) but it is way ahead where potassium (436mg) and vitamin C (14.5mg) are concerned.
4) Red wineA glass of red wine each day keeps the doctor at bay, so we’ve been told. The idea behind this stems from something called the French Paradox. Researchers noticed that despite their high-fat diet, the French have 40% lower occurrence of heart disease than the Americans. This has been attributed to their consumption of red wine, which has large doses of the antioxidant resveratrol. A 100ml serving of red wine has 0.198mg to 0.713mg of resveratrol.
The alternativeIf you’re a teetotaller or would like to stick to a budget, don’t despair. Wong points to grape juice, which is RM3.99 a litre. Tan adds that other foods that have resveratrol include jackfruit and peanuts.
5) SalmonLike blueberries, salmon is a favourite superfood, thanks to its rich bounty of omega-3 essential fatty acids. A 100g serving contains 2,950mg of omega-3 and 490mg of potassium. We’re told to eat salmon two to three times a week to lower our heart disease risk and help prevent arthritis and memory loss. We’re also told to eat wild-caught salmon rather than farm-raised ones because of the chemicals that have been found in the latter. However, at RM99 per kg, the fish is beyond the budget of many households.
The alternativeIndian mackerel (ikan kembung) is a great source of omega-3, with a 100g serving boasting of 1,450mg of omega-3 and 370mg of potassium. Sure, it’s not as chockfull of omega-3 as salmon but at RM10.90 per kg, it’s more affordable. In addition, the humble mackerel also offers more calcium (48mg compared with 12mg in salmon, per 100g serving) and iron (1.8mg vs 0.8mg) and has less fat (3.9g vs 6.34g). Another good alternative is canned sardines (RM3 for a 155g can).
6) WheatgrassOne of the more trendy nutritional wonders, wheatgrass (taken as a juice) is said to have beneficial effects on one’s cholesterol level, blood pressure and immune response, as well as prevent cancer, thanks to its high concentration of chlorophyll. But at RM3.99 for a small cup, it’s pricey.
The alternativeTo enjoy the benefits of chlorophyll, look for green vegetables such as broccoli or spinach. The latter is a great (and more palatable) substitute for wheatgrass and costs only RM1.20 per 100g. A 30g serving of spinach offers 128 mg of potassium (compared with 42 mg per 30ml of wheatgrass juice), 26 mg vitamin C (10mg) and 30mg calcium (7.2mg).
Note: All nutritional information courtesy of Tan Sue Yee, a member of the Nutrition Society of Malaysia. The alternatives proposed are not meant to be exact replacements, as all foods are not created equal. Prices are just indicative and may vary from location to location.
Source: The Edge Malaysia, Images from Yahoo Image search.
Wednesday, February 29, 2012
时间管理的十一条金律

金律一:要和你的价值观相吻合
你一定要确立个人的价值观,假如价值观不明确,你就很难知道什么对你最重要,当你价值观不明确,时间分配一定不好。时间管理的重点不在于管理时间,而在于如何分配时间。你永远没有时间做每件事,但你永远有时间做对你来说最重要的事。
金律二:设立明确的目标
成功等于目标,时间管理的目的是让你在最短时间内实现更多你想要实现的目标;你必须把今年度4到10个目标写出来,找出一个核心目标,并依次排列重要性,然后依照你的目标设定一些详细的计划,你的关键就是依照计划进行。
金律三:改变你的想法
美国心理学之父威廉·詹姆士对时间行为学的研究发现这样两种对待时间的态度:“这件工作必须完成它实在讨厌,所以我能拖便尽量拖”和“这不是件令人愉快的工作,但它必须完成,所以我得马上动手,好让自己能早些摆脱它”。当你有了动机,迅速踏出第一步是很重要的。不要想立刻推翻自己的整个习惯,只需强迫自己现在就去做你所拖延的某件事。然后,从明早开始,每天都从你的list中选出最不想做的事情先做。
金律四:遵循20比80定律.
生活中肯定会有一些突发和迫不及待要解决的问题,如果你发现自己天天都在处理这些事情,那表示你的时间管理并不理想。成功者花最多时间在做最重要的事,而不是最紧急的事情上,然而一般人都是做紧急但不重要的事。
金律五:安排“不被干扰”时间
每天至少要有半小时到一小时的“不被干扰”时间。假如你能有一个小时完全不受任何人干扰,把自己关在自己的空间里面思考或者工作,这一个小时可以抵过你一天的工作效率,甚至有时侯这一小时比你3天工作的效率还要好。
金律六:严格规定完成期限
帕金森(c-NoarthcoteParkinson)在其所著的《帕金森法则》(Parkinsons Law)中,写下这段话:“你有多少时间完成工作,工作就会自动变成需要那么多时间。”如果你有一整天的时间可以做某项工作,你就会花一天的时间去做它。而如果你只有一小时的时间可以做这项工作,你就会更迅速有效地在一小时内做完它。
金律七:做好时间日志
你花了多少时间在做哪些事情,把它详细地记录下来,早上出门(包括洗漱、换衣、早餐等)花了多少时间,搭车花了多少时间,出去拜访客户花了多少时间……把每天花的时间一一记录下来,你会清晰地发现浪费了哪些时间。这和记账是一个道理。当你找到浪费时间的根源,你才有办法改变。
金律八:理解时间大于金钱
用你的金钱去换取别人的成功经验,一定要抓住一切机会向顶尖人士学习。仔细选择你接触的对象,因为这会节省你很多时间。假设与一个成功者在一起,他花了40年时间成功,你跟10个这样的人交往,你不是就浓缩了400年的经验?
金律九:学会列清单
把自己要做的每一件事情都写下来,这样做首先能让你随时都明确自己手头上的任务。不要轻信自己可以用脑子把每件事情都记住,而当你看到自己长长的list时,也会产生紧迫感。
金律十:同一类的事情最好一次把它做完
假如你在做纸上作业,那段时间都做纸上作业;假如你是在思考,用一段时间只作思考;打电话的话,最好把电话累积到某一时间一次把它打完。当你重复做一件事情时,你会熟能生巧,效率一定会提高。
金律十一:每1分钟每1秒做最有效率的事情
你必须思考一下要做好一份工作,到底哪几件事情是对你最有效率的,列下来,分配时间把它做好。(始终直瞄靶心一绩效(司晋升)
source: MBAlib
Friday, February 24, 2012
6 difficulties when applying Letter of Administration (LA)
When a person dies without A Will (Dies intestate) - Apply Letter of Administration (LA)1. Require two guarantors
- Family members might have difficulty to look for the qualified guarantors. The guarantors must have a net worth equivalent to the gross value of the deceased’s estate.
- This results in the delay in estate administration. Beneficiaries might take a longer time to receive their shares of the estate. The delay might result in estate shrinkage and beneficiaries might receive less due to the shrinkage in estate.
2. Conflict & problems faced over the appointment of administrator(s)
- The Court requires 1 or 2 administrator(s).
- Family contention arises over the right to be appointed as the Administrator(s).
- There is risk of the Administrator(s) absconding the estate.
- Appointed Administrator(s) may lack competence to perform.
- Family might not be able to obtain the 100% consent from all legal beneficiaries required.
- When there is a minor beneficiary, two Administrator(s) are needed.
|
|
| 3. Legal Fees higher to apply for LA
|
| 4. Financial difficulties faced by the family as it takes more time to apply for LA
|
5. The Law takes over your ‘RIGHT’ to name your beneficiaries
- As there is no Will, whom your beneficiaries are and the proportion for distribution are decided by the law. The distribution may not be that of your choice, and you lose your Right to distribute your hard earned assets the way you want it.
- Under the Law, there is no provisions for partner, stepchildren, illegitimate children, relatives whom you support.
6. The Law takes over your ‘RIGHT’ to appoint trustees and guardian for your minor children
- If both parents die in a common disaster, the Court decides who are the trustees & guardians for your minor children.
- The appointed person(s) might not be competent to perform the job.
- Welfare of minor might not be taken care of.
- Misuse of funds by the appointed Trustee might happen.
- You lose your Right to choose your preferred trustees/guardian.
Source: Rockwills Sdn. Bhd
Subscribe to:
Posts (Atom)